Every dollar of investment return is compensation for bearing risk, yet the numbers that quantify that risk, volatility, drawdowns, downside exposure, and correlation, are harder to find in one place than return figures. This page compiles the core data behind investment risk analysis, drawn from long-run U.S. market history and primary industry research, across five dimensions: risk-adjusted return benchmarks, volatility and drawdown, downside and tail risk, correlation and diversification, and portfolio risk by allocation.
The data below is sourced from Aswath Damodaran’s NYU Stern historical dataset, the J.P. Morgan Guide to the Markets and Long-Term Capital Market Assumptions, Vanguard’s portfolio research, Hartford Funds and Ned Davis Research, S&P Dow Jones Indices, and Morningstar. Two notes on reading these figures. First, risk statistics such as volatility, Sharpe ratio, and correlation are inherently long-run measures; single-year readings are noisy, so the tables lean on long-run history and layer recent annual returns on top where useful. Second, all figures are U.S.-market data, which is where the deepest risk history exists.
This page is for informational purposes only and does not constitute investment, tax, or financial advice. All figures are drawn from third-party sources believed to be reliable and are subject to revision. Past performance does not guarantee future results, and all investing involves risk, including the possible loss of principal.
1. Risk-Adjusted Return Benchmarks
Higher returns have historically come with higher risk. Over nearly a century, stocks have far outpaced bonds and cash, but with several times the volatility. The Sharpe ratio, which measures return earned per unit of risk above the risk-free rate, lets these asset classes be compared on a level footing. Sharpe figures below are derived using 3-month Treasury bills as the risk-free rate.
Long-run return vs. risk by asset class, 1928 to 2024 (United States)
| Asset class | Annualized return | Annualized volatility | Sharpe ratio (derived) |
| U.S. stocks (S&P 500) | 9.94% | ~18% | ~0.37 |
| U.S. small-cap stocks | 11.74% | ~30% | ~0.28 |
| 10-year Treasury bonds | 4.50% | ~8% | ~0.15 |
| Gold | 5.12% | ~16% | ~0.11 |
| Real estate | 4.23% | n/a (smoothed) | n/a |
| Cash (3-month T-bills) | 3.31% | ~3% | risk-free proxy |
Source: Returns: Damodaran / NYU Stern (1928 to 2024). Volatility: Morningstar / Ibbotson and J.P. Morgan estimates (approximate). Sharpe ratio derived as (return minus T-bill rate) divided by volatility. Real estate volatility is understated by appraisal smoothing.
Risk-adjusted return by sub-asset class (United States)
| Sub-asset | Long-run return | Relative risk |
| Large-cap stocks (S&P 500) | 9.94% | Baseline (~18% volatility) |
| Small-cap stocks | 11.74% | Higher (~30% volatility); deeper drawdowns |
| Investment-grade corporate bonds | ~5% to 6% | Moderate; rate and modest credit risk |
| High-yield (“junk”) bonds | ~7% to 8% | High; equity-like losses in downturns |
Source: Damodaran / NYU Stern; J.P. Morgan Guide to the Markets (credit indices). Sub-asset bond returns are approximate ranges.
Long-run return distribution, S&P 500, 1928 to 2024 (United States)
| Measure | Figure |
| Annualized (compound) return | 9.94% |
| Arithmetic average annual return | 11.79% |
| Median annual return | 14.82% |
| Positive years / total | 71 of 97 (73%) |
| Best year (1954) | +52.56% |
| Worst year (1931) | -43.84% |
Source: Damodaran / NYU Stern, S&P 500 total returns 1928 to 2024.
| Why this matters. Return is the reward for accepting risk, not a free lunch. The job of an advisor is to take only as much risk as a client needs and can tolerate to reach their goals. This is the starting point for how firms like YTS Wealth Management build portfolios around each client’s risk capacity. |
2. Volatility and Drawdown Metrics
Volatility (standard deviation) measures how widely returns scatter around their average; drawdown measures how far an investment falls from a prior peak. Drawdown is what investors actually feel, and it is the risk most likely to drive costly behavior. The figures below show both across asset classes and the historical frequency of market declines.
Volatility and notable maximum drawdown by asset class (United States)
| Asset class | Annualized volatility | Notable maximum drawdown |
| U.S. stocks (S&P 500) | ~18% | ~-57% (2007 to 2009); ~-82% (1929 to 1932) |
| Small-cap stocks | ~30% | Deeper than large-cap in most bears |
| 10-year Treasury bonds | ~8% | ~-17% (2022, worst on record) |
| Investment-grade bonds | ~5% to 7% | ~-17% (2022) |
| Gold | ~16% | ~-60%+ (1980 to 2000) |
| Cash | ~1% to 3% | Minimal in nominal terms |
Source: Morningstar / Ibbotson; S&P Dow Jones Indices; J.P. Morgan. Volatility approximate; drawdowns are peak-to-trough.
Frequency and depth of S&P 500 declines since 1928 (United States)
| Decline type | Threshold | Times since 1928 | Average depth | Average duration |
| Pullback | 3% to 5% | 74 | ~4% | Days |
| Standard correction | 5% to 10% | 51 | ~7% | ~33 days |
| Stronger correction | 10% to 20% | 18 | ~13% | ~129 days |
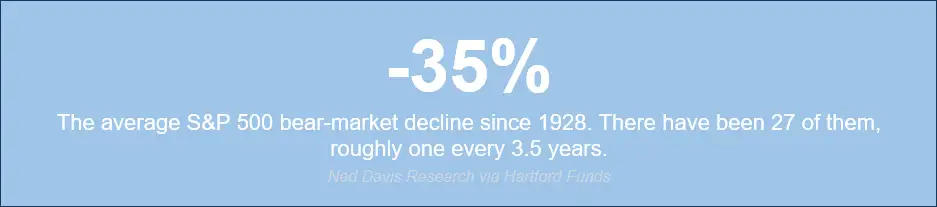
| Bear market | 20%+ | 15 to 27 | ~33% to 35% | ~10 months |
Source: WallStreetCourier analysis of S&P 500 (1928 to 2023); Ned Davis Research via Hartford Funds. Bear-market counts vary by method: closing-price definitions yield ~15 since 1928, intraday definitions (Ned Davis) yield 27; both show an average decline near 33% to 35%.
Recent bear markets and recovery (United States)
| Bear market | Peak-to-trough decline | Time to trough |
| 1929 to 1932 (Great Depression) | ~-82% to -86% | ~3 years |
| 2000 to 2002 (dot-com) | ~-49% | ~2 years |
| 2007 to 2009 (financial crisis) | ~-57% | ~17 months |
| 2020 (COVID-19) | ~-34% | 33 days (fastest on record) |
| 2022 (inflation and rates) | ~-25% | ~9 months |
Source: S&P Dow Jones Indices; Hartford Funds. The average bear lasts ~9.6 months to its trough; full recovery to the prior peak typically takes longer.
| Drawdown is the risk that matters most. Volatility is a statistic, but a deep drawdown is what tempts investors to sell at the bottom and lock in losses. Helping clients size risk so they can hold through a 30%+ decline is central to how YTS Wealth Management approaches portfolio construction. |
3. Downside and Tail Risk
Standard risk measures assume returns follow a normal bell curve, but real markets have fatter tails: extreme losses occur more often than the math predicts. Value-at-Risk (VaR) estimates the loss a portfolio should not exceed in a typical year, while the historical record shows how badly that estimate can understate reality. The VaR table below is illustrative and derived, not drawn from a single published source.
Illustrative annual Value-at-Risk by allocation (derived)
| Portfolio (stocks / bonds) | Expected return | Volatility | 95% one-year VaR | Worst actual one-year loss |
| All-equity (100 / 0) | ~10% | ~18% | ~-20% | ~-44% (1931) |
| Aggressive (80 / 20) | ~9% | ~15% | ~-16% | ~-35% |
| Balanced (60 / 40) | ~8% | ~11% | ~-10% | ~-27% (2008) |
| Conservative (40 / 60) | ~7% | ~8% | ~-6% | ~-18% |
| All-bond (0 / 100) | ~5% | ~6% | ~-5% | ~-17% (2022) |
Source: Illustrative. 95% one-year VaR computed parametrically as (1.65 x volatility) minus expected return, assuming normal returns. The “worst actual” column shows how real tail losses have far exceeded VaR, because returns have fatter tails than the normal model assumes. Inputs from Damodaran and Morningstar; worst years from S&P Dow Jones Indices.
Tail-event frequency and magnitude (United States)
| Tail metric | Figure |
| Years with a 10%+ intra-year drawdown | ~64% of years |
| Years with a bear market (20%+) | ~26% of years |
| Largest stock drawdown (peak-to-trough) | ~-82% (1929 to 1932) |
| Worst single calendar year, stocks | -43.84% (1931) |
| Worst single calendar year, bonds | ~-17% (2022) |
Source: WallStreetCourier; Damodaran; S&P Dow Jones Indices.
Worst single-year loss by asset class (United States)
| Asset class | Worst calendar year | Loss |
| U.S. stocks (S&P 500) | 1931 | -43.8% |
| U.S. small-cap stocks | 1930s | ~-50% (approx.) |
| 10-year Treasury bonds | 2022 | ~-17% |
| Gold | 1981 | ~-33% (approx.) |
Source: Damodaran / NYU Stern; S&P Dow Jones Indices. Figures marked approximate are estimates.
| Plan for the tail, not the average. Because real losses exceed what standard models predict, prudent planning stress-tests a portfolio against severe declines rather than typical ones. Building in that margin of safety is part of how YTS Wealth Management protects clients against the worst-case years. |
4. Correlation and Diversification
Diversification works because assets do not move in lockstep: when correlations are low, combining assets lowers portfolio volatility below the weighted average of the parts. The catch is that correlations are not fixed. They shift across regimes and tend to rise toward 1.0 in a crisis, which is precisely when diversification is needed most. The matrix below shows representative long-run correlations.
Representative long-run cross-asset correlations (United States)
| Stocks | Bonds | Real estate | Commodities | Gold | |
| Stocks | 1.00 | -0.2 to +0.3 | ~0.6 | ~0.25 | ~0.0 |
| Bonds | 1.00 | ~0.2 | ~-0.1 | ~0.3 | |
| Real estate | 1.00 | ~0.2 | ~0.1 | ||
| Commodities | 1.00 | ~0.4 | |||
| Gold | 1.00 |
Source: Representative long-run estimates from J.P. Morgan, Vanguard, and academic research. Correlations shift materially across regimes, especially stocks versus bonds, which has ranged from negative to positive.
Correlation behavior in down markets (United States)
| Indicator | Figure |
| Stock-bond correlation, low-inflation regime | ~-0.3 |
| Stock-bond correlation, 2022 (high inflation) | Positive (~+0.5) |
| Cross-stock correlations during crises | Rise toward 1.0 |
| International vs. U.S. stock correlation | ~0.6 to 0.9 (rises in crises) |
Source: J.P. Morgan Guide to the Markets; academic research. Diversification weakens precisely when it is needed most, as correlations converge in sell-offs.
Diversification benefit by correlation regime, 60/40 portfolio (United States)
| Scenario | Weighted-average volatility | Actual portfolio volatility |
| Negative stock-bond correlation (-0.3) | 13.2% | ~11% |
| Positive stock-bond correlation (+0.5, 2022-like) | 13.2% | ~12.5% |
Source: Illustrative portfolio math. The volatility reduction from diversification depends entirely on correlation and shrinks when stocks and bonds move together.
| Diversification is dynamic, not automatic. Because correlations rise in crises, a portfolio that looks diversified in calm markets can concentrate risk in a sell-off. Monitoring those relationships and adjusting accordingly is an active part of risk management at YTS Wealth Management. |
5. Portfolio Risk by Allocation
The single biggest driver of a portfolio’s risk is its stock-to-bond mix. Moving from conservative to aggressive raises both expected return and the size of the losses an investor must be able to withstand. The figures below are long-run historical approximations based on the standard allocation-model framework; forward-looking return expectations are lower.
Risk and return by allocation model, long-run (United States)
| Allocation (stocks / bonds) | Annualized return | Volatility | Worst calendar year |
| All-equity (100 / 0) | ~10.2% | ~18% | ~-43% |
| Aggressive (80 / 20) | ~9.6% | ~15% | ~-35% |
| Balanced (60 / 40) | ~8.8% | ~11% | ~-27% |
| Conservative (40 / 60) | ~7.7% | ~8% | ~-18% |
| Income (20 / 80) | ~6.6% | ~6% | ~-10% |
| All-bond (0 / 100) | ~5.3% | ~5% | ~-8% |
Source: Long-run historical (approximately 1926 to 2024), based on the Vanguard allocation-model framework and component returns from Damodaran. Approximate. For context, J.P. Morgan’s 2026 forward assumptions project a 60/40 at 6.4% annually, well below the historical 8.8%.
Risk contribution by component, 60/40 portfolio (United States)
| Component | Capital weight | Share of portfolio risk |
| Equities | 60% | ~90% |
| Bonds | 40% | ~10% |
Source: Standard portfolio risk decomposition; J.P. Morgan and Vanguard. Because stocks are far more volatile, a 60/40 portfolio’s risk is dominated by its equity sleeve.
Rebalancing impact on portfolio risk (United States)
| Approach | Effect on risk |
| Periodic rebalancing (e.g., annual) | Keeps volatility near the target allocation |
| No rebalancing (drift) | Equity weight and volatility climb through bull markets |
| Rebalancing discipline | Sells high and buys low; modest long-run benefit |
Source: Vanguard research on rebalancing. A 60/40 left un-rebalanced through a long bull market can drift toward 75/25 and materially higher risk.
| Allocation is the lever. More than any single holding, the stock-bond mix determines how much risk a client carries. Matching that allocation to each client’s goals, time horizon, and tolerance for loss is the core of the work at YTS Wealth Management. |
Understand the risk in your own portfolio.
Talk through a risk analysis with YTS Wealth Management
References
- Damodaran, Aswath (NYU Stern). “Historical Returns on Stocks, Bonds and Bills: 1928 to 2024.” pages.stern.nyu.edu/~adamodar. Accessed June 2026. (Asset-class returns and worst years.)
- Hartford Funds / Ned Davis Research. “10 Things You Should Know About Bear Markets.” hartfordfunds.com. Accessed June 2026. (27 bear markets; average -35% over ~9.6 months; one every ~3.5 years.)
- “S&P 500 Drawdowns Analysis, 1928 to 2023.” wallstreetcourier.com. Accessed June 2026. (Pullback, correction, and bear-market frequency and depth.)
- P. Morgan Asset Management. “Guide to the Markets,” 2026 editions. am.jpmorgan.com. Accessed June 2026. (Asset-class volatility, correlations, and risk-return.)
- P. Morgan Asset Management. “2026 Long-Term Capital Market Assumptions.” Published October 20, 2025. am.jpmorgan.com. Accessed June 2026. (Forward 60/40 return of 6.4%.)
- “Portfolio allocation models” and Vanguard Capital Markets Model research. investor.vanguard.com; corporate.vanguard.com. Accessed June 2026. (Allocation-model risk/return; rebalancing.)
- Morningstar / Ibbotson Associates. Asset-class volatility and Sharpe-ratio data. morningstar.com. Accessed June 2026.
- S&P Dow Jones Indices. S&P 500 drawdown and bear-market data. spglobal.com. Accessed June 2026.
- Federal Reserve Bank of St. Louis (FRED). 3-month Treasury bill rate (risk-free rate for Sharpe calculations). fred.stlouisfed.org. Accessed June 2026.