Net worth varies enormously by age. A typical household in its late twenties holds a small fraction of what a typical household in its late sixties has, and within every age group the distance between the middle and the top is wide. This article shows where net worth falls by percentile within each age group in the United States, from the 25th percentile through the top 1%, and how the median compares to the average across the life cycle.
The figures below come from the Federal Reserve’s Survey of Consumer Finances, the most authoritative source of U.S. household wealth data, using the 2022 survey released in October 2023. It remains the most recent complete dataset, since the 2025 survey is still underway with results expected in late 2026. Percentile-by-age breakpoints are computed from the survey’s public microdata. Figures reflect households grouped by the age of the head of household, are stated in 2022 to 2023 dollars, and are rounded. Upper percentiles, especially the top 1%, carry wider margins of error because fewer households fall into them.
This article is for informational purposes only and does not constitute investment, tax, or financial advice. Net worth is one measure of financial health and does not reflect income, cash flow, or individual circumstances. Consult a qualified financial professional for guidance specific to your situation.
Net Worth Percentiles by Age
Key finding: Within every age group, net worth rises steeply from the 25th percentile to the 90th, and that spread widens with age as wealth compounds for those who are already ahead.
The table below shows household net worth at the 25th, 50th (median), 75th, and 90th percentiles for each age bracket. A household at the median has more net worth than half of its age peers and less than the other half. The jump from the median to the 90th percentile is far larger than the jump from the 25th to the median, which reflects how concentrated wealth becomes near the top of each age group.
Table 1: Net worth by percentile and age (2022)
| Age | 25th | Median | 75th | 90th |
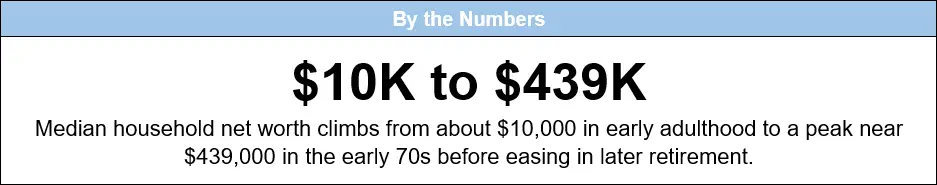
| 18 to 24 | $100 | $10K | $34K | $185K |
| 25 to 29 | $4K | $31K | $131K | $297K |
| 30 to 34 | $11K | $89K | $186K | $539K |
| 35 to 39 | $17K | $139K | $389K | $864K |
| 40 to 44 | $24K | $134K | $437K | $1.2M |
| 45 to 49 | $48K | $214K | $680K | $1.4M |
| 50 to 54 | $54K | $266K | $913K | $2.6M |
| 55 to 59 | $85K | $321K | $1.1M | $2.7M |
| 60 to 64 | $80K | $393K | $1.1M | $3.0M |
| 65 to 69 | $69K | $393K | $1.2M | $3.0M |
| 70 to 74 | $125K | $439K | $1.2M | $3.0M |
| 75 to 79 | $90K | $338K | $992K | $2.9M |
| 80 plus | $95K | $327K | $944K | $2.5M |
For perspective, it helps to see where these age-specific numbers sit against the national picture. Across all ages, the median U.S. household net worth was about $193,000 in 2022, while the thresholds for the top brackets ran far higher.
Table 2: National net worth benchmarks, all ages (2022)
| Percentile | Net worth threshold |
| Median (50th percentile) | $193K |
| Top 10% | $1.9M |
| Top 5% | $3.8M |
| Top 1% | $13.7M |
Median Versus Average Net Worth by Age
Key finding: Average net worth runs roughly four to five times the median at almost every age, because a small number of very wealthy households pull the average sharply upward.
Average, or mean, net worth is a poor guide to a typical household because it is distorted by the wealthiest few. The median, the midpoint of the distribution, is a more realistic benchmark for most people. The gap between the two is a useful measure of how skewed wealth is within each age group.
Table 3: Median and average net worth by age (2022)
| Age | Median | Average | Average vs. median |
| 18 to 24 | $10K | $112K | 11x |
| 25 to 29 | $31K | $120K | 4x |
| 30 to 34 | $89K | $258K | 3x |
| 35 to 39 | $139K | $501K | 4x |
| 40 to 44 | $134K | $591K | 4x |
| 45 to 49 | $214K | $782K | 4x |
| 50 to 54 | $266K | $1.1M | 4x |
| 55 to 59 | $321K | $1.4M | 4x |
| 60 to 64 | $393K | $1.7M | 4x |
| 65 to 69 | $393K | $1.8M | 5x |
| 70 to 74 | $439K | $1.7M | 4x |
| 75 to 79 | $338K | $1.6M | 5x |
| 80 plus | $327K | $1.6M | 5x |
Both measures follow the same life-cycle arc: net worth builds through the working years, peaks around retirement, and then eases as households spend down savings. The average peaks slightly earlier than the median, in the mid-to-late 60s.
Table 4: When net worth peaks across the life cycle
| Measure | Peak age | Peak value | Value at 80 plus |
| Median net worth | 70 to 74 | $439K | $327K |
| Average net worth | 65 to 69 | $1.8M | $1.6M |
The Top Brackets by Age
Key finding: The net worth needed to reach the top brackets climbs sharply with age, peaking in the mid-to-late 60s before easing as older households draw down their wealth.
The gap between a comfortable position and the very top of an age group is large and grows with age. The table below shows the net worth required to reach the 90th percentile and the top 1% within each bracket. Reaching the top 1% takes a few hundred thousand dollars in early adulthood but tens of millions by the mid-60s.
Table 5: 90th percentile and top 1% net worth by age (2022)
| Age | 90th percentile | Top 1% |
| 18 to 24 | $185K | $653K |
| 25 to 29 | $297K | $2.1M |
| 30 to 34 | $539K | $2.6M |
| 35 to 39 | $864K | $4.7M |
| 40 to 44 | $1.2M | $7.8M |
| 45 to 49 | $1.4M | $8.7M |
| 50 to 54 | $2.6M | $13.2M |
| 55 to 59 | $2.7M | $15.4M |
| 60 to 64 | $3.0M | $17.9M |
| 65 to 69 | $3.0M | $22.1M |
| 70 to 74 | $3.0M | $18.8M |
| 75 to 79 | $2.9M | $19.9M |
| 80 plus | $2.5M | $16.2M |
The top 1% threshold roughly triples from the early 30s to the late 40s and then keeps climbing, reaching about $22.1 million for households headed by someone 65 to 69 before falling back in the oldest brackets.
Table 6: The top 1% climb at key ages (2022)
| Age | Top 1% net worth |
| 30 to 34 | $2.6M |
| 45 to 49 | $8.7M |
| 55 to 59 | $15.4M |
| 65 to 69 (peak) | $22.1M |
| 80 plus | $16.2M |
A Note on Methodology
All figures are drawn from the Federal Reserve’s 2022 Survey of Consumer Finances, the most recent complete edition, with percentile-by-age breakpoints computed from the survey’s public microdata. Households are grouped by the age of the head of household, and values are in 2022 to 2023 dollars and rounded to two significant figures. Because the survey is conducted only every three years, these benchmarks predate recent movements in housing and equity markets, and the 2025 edition is expected in late 2026. Upper percentile figures, particularly the top 1%, are based on smaller samples and carry wider margins of error.
See Where You Stand and Build a Plan
Knowing your percentile is a starting point, not a verdict. What matters more is the trajectory: whether your savings, investments, and home equity are on track for your goals at your stage of life. A qualified, licensed financial advisor can help you build a plan with the goal of helping you.
Talk to YTS Wealth Management about your financial plan
References
- Federal Reserve Board, Survey of Consumer Finances (2022), released October 2023. federalreserve.gov (accessed June 2026).
- DQYDJ, “Net Worth by Age Percentile Calculator” and “Net Worth Percentiles,” computed from the 2022 Survey of Consumer Finances. dqydj.com (accessed June 2026).
- Fidelity Investments, “Average and median net worth by age,” citing the Federal Reserve Survey of Consumer Finances. fidelity.com (accessed June 2026).
Data is presented for informational purposes and reflects the most recent Survey of Consumer Finances available as of June 2026. Figures are rounded and estimates for the highest percentiles carry wider margins of error. This article does not constitute investment, tax, or financial advice.