Asset allocation looks very different at different levels of net worth. A household in the middle of the wealth distribution holds most of its net worth in a home, while the wealthiest hold most of theirs in financial assets and private businesses. Within investment portfolios, the mix tilts further toward equities and private markets as wealth rises, and even at the same wealth level, age and concentration reshape the picture. This article breaks down how allocation shifts across the wealth ladder, from typical households to high-net-worth and ultra-high-net-worth investors, and what drives those differences.
The figures below draw on the Federal Reserve’s 2022 Survey of Consumer Finances and Distributional Financial Accounts for household net worth composition, the Capgemini World Wealth Report 2026 for high-net-worth portfolio allocation as of January 2026, and the Bank of America Private Bank Study of Wealthy Americans for allocation by generation. Household tiers are defined by net worth percentile, while high-net-worth tiers are defined by investable assets of one million dollars or more excluding a primary residence, so the two lenses use related but distinct yardsticks. Figures are rounded and reflect the most recent data available as of June 2026.
This article is for informational purposes only and does not constitute investment, tax, or financial advice. Asset allocation should reflect an individual’s goals, time horizon, risk tolerance, and circumstances. Consult a qualified financial professional before making investment decisions.
How Net Worth Is Composed Across Wealth Tiers
Key finding: For most households, net worth is concentrated in a home. Financial assets and private business ownership only come to dominate the balance sheet at the very top of the wealth distribution.
The 2022 Survey of Consumer Finances places median household net worth at about $162,000, the 90th percentile at roughly $1.56 million, and the entry point to the top 1% at about $11.6 million. Across those tiers, the composition of assets changes dramatically. Real estate is the largest holding for households from the 25th through the 99th percentile, and only at the very top do stocks and private business equity outweigh the home.
Table 1: Share of total assets by net worth tier (2022)
| Asset category | 25th to 50th | 50th to 75th | 75th to 99th | Top 1% |
| Real estate | 72% | 72% | 52% | 22% |
| Stocks and funds | 6% | 12% | 27% | 30% |
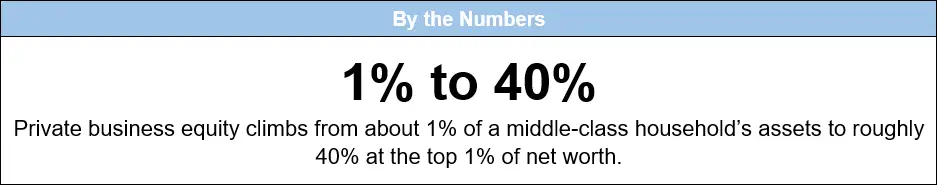
| Private business | 1% | 2% | 8% | 40% |
| Cash and other financial | 8% | 8% | 9% | 7% |
| Vehicles and other assets | 13% | 6% | 4% | 1% |
The pattern is a steady handoff. In the lower-middle tiers, roughly seven in ten dollars of assets sit in real estate, much of it leveraged with a mortgage. As net worth rises, stocks grow from a small slice to nearly a third of assets, and private business equity, negligible for most households, becomes the single largest category at the top.
Table 2: Where wealth concentrates, by net worth tier (2022)
| Net worth tier | Real estate share | Stocks and business share |
| 25th to 50th percentile | 72% | 7% |
| 50th to 75th percentile | 72% | 14% |
| 75th to 99th percentile | 52% | 35% |
| Top 1% | 22% | 70% |
Investment Allocation by Wealth Band
Key finding: Among high-net-worth investors, portfolios spread across equities, real estate, cash, and fixed income, with a persistent and growing tilt toward alternatives and private markets as wealth rises.
High-net-worth individuals, defined as those with at least one million dollars in investable assets, hold a more diversified investment mix than the typical household. As of January 2026, a strong equity market pulled cash off the sidelines and equities became the largest single allocation. Alternatives dipped as public stocks outperformed, but appetite for private markets remained high.
Table 3: High-net-worth portfolio allocation, January 2026
| Asset class | Share of portfolio |
| Equities | 25% |
| Real estate | 22% |
| Cash and cash equivalents | 21% |
| Fixed income | 20% |
| Alternative investments | 12% |
That mix is not static across wealth bands. The wealthiest investors lean hardest into private markets, and demand for alternatives rises with net worth. Two in three high-net-worth investors intend to increase private equity exposure, and most say they work with more than one firm specifically to reach those opportunities.
Table 4: How allocation tilts with wealth (2025 to 2026)
| Signal | Figure |
| HNWIs intending to increase private equity exposure | 68% |
| HNWIs using multiple firms to access alternatives | 88% |
| UHNW ($25M+) who favor private over public markets | 77% |
| Share of HNWI wealth held by the top 1% of HNWIs | 34.8% |
What Drives Allocation Beyond Net Worth
Key finding: At the same wealth level, age reshapes allocation. Younger wealthy investors hold far less in stocks and far more in alternatives and cryptocurrency than older ones.
Net worth is not the only thing that moves a portfolio. Among wealthy Americans with at least three million dollars in investable assets, younger investors allocate roughly half as much to traditional stocks and bonds as older investors, and several times more to alternatives and digital assets. The gap reflects a generational skepticism that stocks and bonds alone can deliver above-average returns.
Table 5: Portfolio allocation by generation among wealthy investors (2024)
| Asset type | Younger (21 to 43) | Older (44+) |
| Stocks and bonds | 47% | 74% |
| Alternative investments | 17% | 5% |
| Cryptocurrency | 14% | 1% |
The 2026 edition of the same study shows the tilt holding and, in digital assets, deepening. Younger investors continue to carry double-digit allocations to alternatives and crypto, and the large majority plan to add more, a pace older generations do not match.
Table 6: Where younger wealth is heading (2026)
| Signal | Figure |
| Younger investors’ alternatives allocation | 15% |
| Younger investors’ cryptocurrency allocation | 13% |
| Younger investors who own cryptocurrency | 58% |
| Younger investors likely to increase alternatives | 88% |
| Boomers and Silents likely to increase alternatives | 15% |
A Note on Methodology
Two different measures of wealth appear in this article. Household composition in Section 1 is grouped by net worth percentile and covers all U.S. households, drawn from the Federal Reserve’s Survey of Consumer Finances. High-net-worth and generational figures in Sections 2 and 3 are grouped by investable assets, excluding a primary residence, and cover the wealthy investor population surveyed by Capgemini and Bank of America. The two are related but not identical scales, and shares are rounded. In the January 2026 high-net-worth allocation, equities, fixed income, and alternatives are reported directly by Capgemini; cash and real estate are shown within the combined remainder that report describes.
Plan an Allocation That Fits Your Net Worth
Every tier of net worth carries a different set of allocation questions, from concentration in a home or a business to the right role for alternatives. A qualified licensed financial advisor can help align your mix with your goals, time horizon, and risk tolerance.
Talk to YTS Wealth Management about your portfolio
References
- Federal Reserve Board, Survey of Consumer Finances (2022) and Distributional Financial Accounts. federalreserve.gov (accessed June 2026).
- Federal Reserve Bank of Richmond, “Portfolios Across the U.S. Wealth Distribution,” Economic Brief No. 23-39 (November 2023). richmondfed.org (accessed June 2026).
- Capgemini Research Institute, World Wealth Report 2026 (June 2026; portfolio allocation as of January 2026). capgemini.com (accessed June 2026).
- Bank of America Private Bank, Study of Wealthy Americans, 2024 and 2026 editions (respondents with $3 million or more in investable assets). bankofamerica.com (accessed June 2026).
Data is presented for informational purposes and reflects the most recent figures available as of June 2026. Percentages are rounded and may not sum to exactly 100. This article does not constitute investment, tax, or financial advice.