Wealth management is one of the largest and fastest-evolving segments of global financial services, yet reliable figures on its size, clients, pricing, and workforce are scattered across dozens of industry reports that rarely agree on definitions. This page compiles the most current wealth management data available as of mid-2026, drawn from primary industry research, and presents it across five dimensions: market size, client and asset distribution, fees and pricing, digital and robo-advisory adoption, and the advisor landscape.
The data below is sourced from the Capgemini World Wealth Report, the BCG Global Wealth and Asset Management reports, PwC’s Global Asset and Wealth Management Report, Cerulli Associates’ U.S. Advisor Metrics, Kitces Research, and Statista. One note on reading these numbers: “wealth management” is measured several different ways. Total global financial wealth (roughly $305 trillion), the investable wealth of millionaires (roughly $98 trillion), global asset management AUM (roughly $128 to $147 trillion), and U.S. advisor-managed retail assets (roughly $31 trillion) are different denominators, not contradictory figures. Each table notes which measure it uses, and tables specific to the United States are labeled accordingly.
This page is for informational purposes only and does not constitute investment, tax, or financial advice. All figures are drawn from third-party sources believed to be reliable and are subject to revision. Past performance does not guarantee future results.
- Wealth Management Market Size
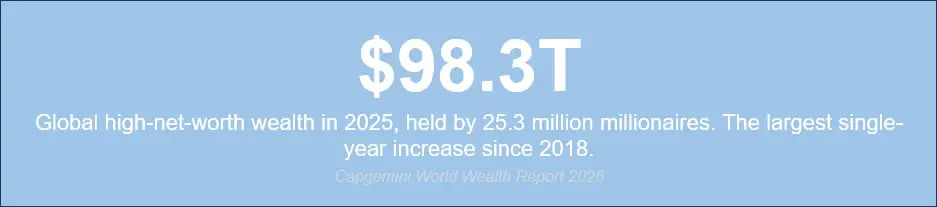
By any measure, the wealth management market reached record size in 2025. Global asset management assets under management (AUM) climbed to roughly $147 trillion, while the investable wealth held by high-net-worth individuals rose 8.7% to a record $98.3 trillion. Growth, however, has leaned heavily on market performance rather than new client inflows, a vulnerability that industry researchers have repeatedly flagged.
Global market size benchmarks, 2024 to 2025 (Global)
| Measure | 2024 | 2025 | Growth |
| Global asset management AUM | $128T | $147T | +12% in 2024 |
| Global HNWI investable wealth | $90.5T | $98.3T | +8.7% |
| Global HNWI population | 23.4M | 25.3M | +7.9% |
| Global financial wealth (all households) | $305T | n/a | record high |
Source: BCG Global Asset Management Report 2025; BCG Global Wealth Report 2025; Capgemini World Wealth Report 2025 and 2026.
Projected global growth to 2030 (Global)
| Measure | 2024 | 2030 (projected) | CAGR |
| Global assets under management | $139T | $200T | 6.2% |
| Total investable wealth worldwide | $345T | $482T | 5.7% |
| Mass affluent wealth | growing | 5.7% CAGR | 5.7% |
| HNWI wealth | growing | 6.5% CAGR | 6.5% |
Source: PwC 2025 Global Asset and Wealth Management Report.
HNWI growth by region, 2025 (Global)
| Region | HNWI population growth 2025 | Projected annual wealth growth to 2029 |
| Asia-Pacific | +9.4% | ~9% |
| North America | +9.1% | ~4% |
| Europe | +6.5% | ~5% |
| Africa | +4.1% | n/a |
| Latin America | +0.3% | n/a |
| Middle East | -1.4% | n/a |
Source: Capgemini World Wealth Report 2026; BCG (forward regional projections).
U.S. wealth management assets by channel (United States)
| Channel | Advisor headcount share | Asset market share |
| Wirehouse | ~15% | ~34% (largest) |
| National / regional broker-dealer | ~15% | ~16% |
| Independent broker-dealer | ~16.5% | ~12.7% |
| Independent RIA | ~16% | ~16% |
| Hybrid RIA | ~13% | ~11% |
Source: Cerulli U.S. Advisor Metrics (2023 to 2025). Independent and hybrid RIAs combined held roughly 27% of assets in 2025, up from 21% in 2014, and are projected to exceed 30%.
| What this means for independent firms. With more than 80% of industry revenue growth tied to market performance rather than new client assets, organic growth has become the real differentiator. The fastest gains in asset share continue to flow to independent and hybrid RIAs, the model that firms like YTS Wealth Management compete in. |
- Client and Asset Distribution
Wealth is highly concentrated. Ultra-high-net-worth individuals, those with $30 million or more, make up just 1% of the millionaire population but control more than a third of all high-net-worth wealth. Understanding how clients and assets distribute across segments is central to how wealth management firms position their services and set minimums.
Global wealth distribution by segment, 2024 (Global)
| Segment (investable assets) | Share of HNWI population | Share of HNWI wealth | Growth |
| Mass affluent ($100K to $1M) | not in HNWI models | n/a | 5.7% CAGR (PwC) |
| Millionaires next door ($1M to $5M) | 89.8% | ~43% | 6.5% CAGR (PwC) |
| Mid-tier millionaires ($5M to $30M) | 9.2% | ~23% | n/a |
| UHNWI ($30M and above) | 1.0% | 34% | +9.4% pop (2025) |
Source: Capgemini World Wealth Report 2025 (population and wealth shares; UHNWI count 234,000); PwC 2025 (segment growth). Within-band wealth shares derived from Capgemini’s reported figures (HNWIs over $5M hold 57% of wealth; UHNWIs hold 34%).
HNWI population by region, 2024 (Global)
| Region | HNWIs (millions) |
| North America | 8.4 |
| Asia-Pacific | 7.7 |
| Europe | 5.7 |
| Middle East | 0.9 |
| Latin America | 0.6 |
| Africa | 0.2 |
Source: Capgemini World Wealth Report 2025.
Average investable wealth per individual by segment (Global)
| Segment | Approx. average investable wealth |
| All HNWIs (2025) | ~$3.9M (derived) |
| UHNWIs, $30M and above (2025) | ~$130M+ (derived) |
| U.S. robo-advisor account (mass-retail proxy) | ~$79,600 |
Source: Derived from Capgemini aggregates ($98.3T across 25.3M HNWIs); Statista (average U.S. robo-advisor account, 2025).
| The generational inflection. An estimated $83.5 trillion will pass to younger investors by 2048, and 81% of inheritors say they will change firms within one to two years of inheriting. Retaining the next generation, not just the current client, is the defining growth challenge for firms like YTS Wealth Management over the coming decade. |
- Fees and Pricing
The percentage-of-assets (AUM) fee remains the dominant pricing model in U.S. wealth management, used by roughly 92% of advisors. Headline rates still cluster near 1%, but graduated fee schedules mean the blended rate falls steadily as portfolios grow, and fee compression continues at the margins. The figures below are U.S. benchmarks.
Typical blended advisory fee by portfolio size (United States)
| Portfolio size | Typical blended AUM fee |
| Under $1 million | 1.00% to 1.20% |
| $1 million | ~1.00% (62% of advisors charge 1% or more) |
| $2 million | 0.80% to 1.00% (only 32% charge 1% or more) |
| $3 million | ~0.85% |
| $5 million and above | 0.50% to 0.80% |
Source: Kitces Research (blended all-in advisory fees). Rates reflect graduated schedules; the median fee runs near 1% up to $1M and declines above $2M.
Fee model usage among U.S. advisors (United States)
| Fee model | Usage or typical rate |
| AUM-based | ~92% of advisors use it; 62% as their primary model |
| Standalone financial plan | median ~$3,000 |
| Subscription / retainer | median ~$4,500 per year |
| Hourly | median ~$300 per hour |
Source: Kitces Research; Envestnet / MoneyGuide State of Financial Planning Fees.
Fee compression indicators (United States and Global)
| Indicator | Figure |
| Advisors charging 1% or more at $1M | 62% |
| Advisors charging 1% or more at $2M | 32% |
| Planning share of a bundled AUM fee | ~41% |
| Annual decline in institutional fees | ~3% (BCG) |
| Robo-advisor median fee | 0.25% |
Source: Kitces Research; BCG Global Asset Management Report; Morningstar.
| Transparency as the differentiator. As fee compression persists and AUM pricing stays dominant, clear and conflict-free pricing increasingly sets firms apart. Fee transparency is central to how firms like YTS Wealth Management build trust with prospective clients. |
- Digital and Robo-Advisory Trends
Automated investing has scaled into a multi-trillion-dollar segment, but its growth rate has cooled as the market matures, and the industry is converging on hybrid models that pair digital tools with human advisors. The AUM figures below are U.S.-specific; note that many widely cited “robo market size” reports measure software revenue rather than assets and should not be confused with AUM.
U.S. robo-advisor assets under management (United States)
| Year | Robo-advisor AUM | Notes |
| 2024 (est.) | ~$1.61T | interpolated at 3.5% CAGR |
| 2025 | $1.67T | ~$79,600 average per user |
| 2026 (est.) | ~$1.72T | interpolated at 3.5% CAGR |
| 2029 (projected) | $1.91T | 21.2M users; 3.5% CAGR 2025 to 2029 |
Source: Statista Robo-Advisors market forecast (United States). 2024 and 2026 figures interpolated from the published 2025 value and 3.5% CAGR.
Hybrid versus fully digital adoption (Global, estimates)
| Indicator | Estimate |
| Hybrid share of the robo-advisory market | ~45% |
| Traditional advisors partnering with digital platforms | ~40% |
| Hybrid models as a share of advisory adoption | ~35% |
Source: Industry estimates (varies by source; the softest data on this page, included directionally).
Advisor and client digital sentiment (Global)
| Indicator | Figure |
| Advisors who want AI to automate routine work | 3 in 4 (75%) |
| Advisors dissatisfied with their firm’s digital tools | ~33% |
| HNWIs who find their advisory experience seamless | 17% |
| WM firms still segmenting clients mainly by wealth band | 97% |
Source: Capgemini World Wealth Report 2026.
- Advisor Landscape and Performance
The advisor workforce is large but barely growing, and it faces a demographic reckoning. Headcount has risen just 0.2% over the past decade even as managed assets have climbed, and more than a third of advisors plan to retire within ten years, creating a succession gap that is reshaping the competitive landscape. The figures below are U.S. benchmarks from Cerulli Associates.
U.S. financial advisor metrics (United States)
| Metric | Figure |
| Total financial advisors (2023) | 283,137 (+0.2% over the decade) |
| Retail advisor-managed assets (2023) | $31.3 trillion |
| Average AUM per advisor, all channels | ~$88 million |
| Average AUM per advisor, wirehouse | ~$198 million |
| Average AUM per advisor, large RIA ($5B+) | ~$184 million |
| Client satisfaction with their advisor | ~80% |
Source: Cerulli U.S. Advisor Metrics.
Advisor retirement and succession gap (United States)
| Indicator | Figure |
| Advisors planning to retire within 10 years | 105,887 (37% of headcount) |
| Share of industry assets they control | 41% |
| Near-retirement advisors unsure of a succession plan | 26% (30% among RIAs) |
| Rookie advisors who fail within five years | 71% |
Source: Cerulli U.S. Advisor Metrics.
Net asset flows and channel growth (United States)
| Channel | Annual AUM growth |
| Hybrid RIA | ~12.2% |
| Independent RIA | ~10.9% |
| Wirehouse | ~8.6% |
Source: Cerulli. Independent and hybrid RIA assets reached ~$9.8 trillion in 2025 (up from $6.6 trillion in 2019). In 2025, roughly 9% of advisors representing $3.1 trillion changed firms, and about 300 RIAs with $5B or more now hold 54% of all RIA assets.
| The succession cliff and the shift to independence. With roughly $3.9 trillion expected to change hands inside the industry over the next five to ten years and RIA assets concentrating among large firms, scale and continuity planning are becoming decisive. These are exactly the dynamics independent firms like YTS Wealth Management are navigating. |
Put this data to work for your own financial plan.
Connect with the team at YTS Wealth Management
References
- Capgemini Research Institute. “World Wealth Report 2026.” Published June 4, 2026. capgemini.com/insights/research-library/world-wealth-report. Accessed June 2026.
- Capgemini Research Institute. “World Wealth Report 2025.” Published June 2025. capgemini.com. Accessed June 2026. (HNWI population and wealth by region and band, 2024.)
- Boston Consulting Group. “Global Wealth Report 2025: Rethinking Rules for Growth.” bcg.com/publications/2025/global-wealth-report-2025. Accessed June 2026. ($305T global financial wealth.)
- Boston Consulting Group. “Global Asset Management Report 2025.” bcg.com. Accessed June 2026. ($128T AUM in 2024, +12%; $147T in 2025.)
- “2025 Global Asset and Wealth Management Report.” Published November 24, 2025. pwc.com. Accessed June 2026. (Global AuM $139T to $200T by 2030; investable wealth $345T to $482T.)
- Kitces Research. “How Financial Advisors Actually Charge For Their Services” and related fee studies. kitces.com. Accessed June 2026.
- Envestnet / MoneyGuide. “2026 State of Financial Planning Fees.” Accessed June 2026.
- “Robo-Advisors, United States, Market Forecast.” statista.com. Accessed June 2026. (US robo AUM ~$1.67T in 2025; ~$1.91T by 2029.)
- Cerulli Associates. “U.S. Advisor Metrics 2024 and 2025.” cerulli.com. Accessed June 2026. (Advisor headcount, AUM per advisor, succession, channel share.)
- Cerulli Associates. “The RIA Marketplace 2026.” cerulli.com. Accessed June 2026. (RIA asset concentration and intra-industry asset movement.)
- Robo-advisor median fee data. morningstar.com. Accessed June 2026.